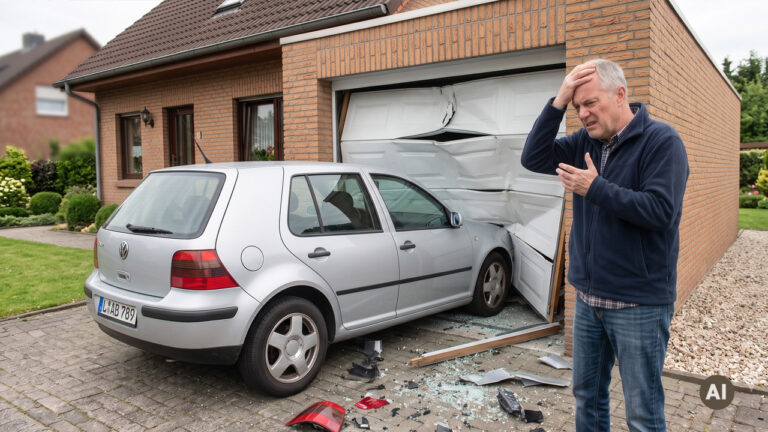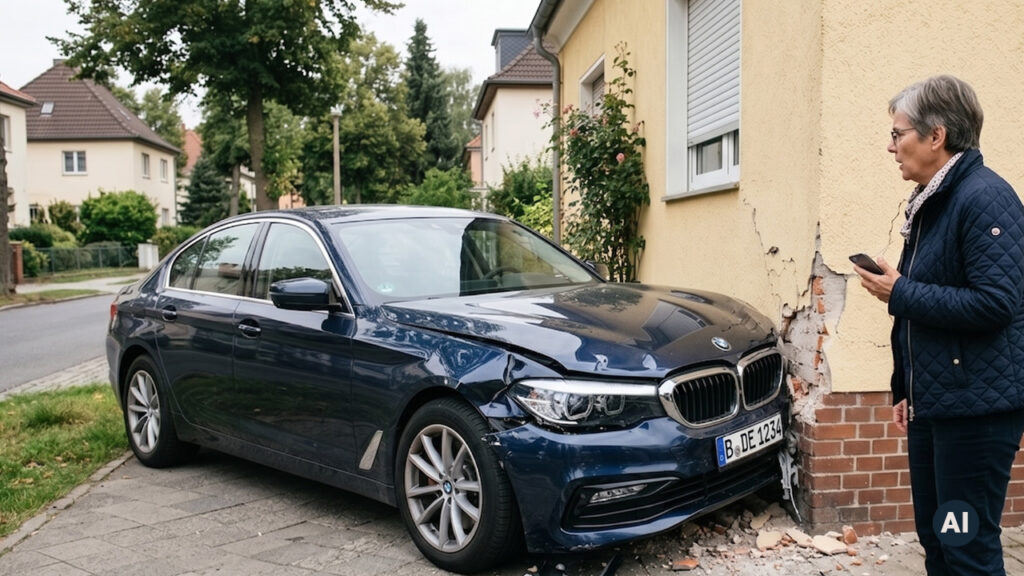
If a car crashes into the wall of a house, the person responsible for the accident – or their motor vehicle liability insurance – is generally liable for the damage caused to the building. It is important to document the damage immediately, secure the scene of the accident and have any potential structural damage assessed by a professional.
An accident of this kind can have serious consequences: as well as visible damage to the façade, windows or masonry, load-bearing elements, pipework or the structural integrity of the building may also be affected. As a result, settling a claim following an accident involving a building wall is often considerably more complex than in the case of a standard road traffic accident.
In this guide, you will find out what to do immediately after an accident, who is liable for damage to the house wall, which insurance company is responsible, and how to make a claim correctly. We also explain the specific considerations for accidents involving lorries, tractors and other vehicles.
- Securing the scene of an accident & the rescue chain: If there are injured people or an immediate danger, dial the emergency number 112 or the police on 110. Attend to any injured people and leave the danger zone, provided it is safe to do so.
- Warning: Risk of collapse: If a vehicle has crashed into the wall of a house, it must under no circumstances be pulled out of the masonry without authorisation. The vehicle may be propping up parts of the damaged structure, and removing it could increase the risk of collapse.
- Who pays for the damage? If the homeowner is not responsible for the accident, the motor vehicle liability insurance of the person who caused the accident will usually cover the damage resulting from the accident. This may include, amongst other things, damage to the masonry as well as the costs of expert reports, structural engineers and any other necessary measures.
- Consult independent experts: In the event of significant damage to a building, it may be advisable to call in an independent building surveyor to document the nature and extent of the damage professionally.
- Carry out the claims settlement in full: In addition to the immediate repair costs, further claims may arise depending on the individual case, such as costs for alternative accommodation, loss of use or loss of rent.
Accident victims like you get the best support from fairforce.one.
Have your accident reported now free of charge and without obligation by our regulation specialists.
When a car crashes into the side of a house: Initial assessment & first steps to be taken directly at the scene of the accident
If a car crashes into the wall of a house, the safety of everyone involved is the top priority. Both the driver and the residents of the building in question are usually in a state of shock.
Quick check: The procedure for the first few minutes on site:
-
Personal safety & calling for help: Secure the scene, switch on your hazard warning lights and immediately dial the emergency numbers 112 (ambulance service / fire brigade) and 110 (police).
-
Evacuating a building: Residents should leave the affected room and, as a precaution, the building. There is a risk of further damage to load-bearing structures and to gas, water or electricity pipes and cables.
-
STRICT PROHIBITION: DO NOT attempt to pull the vehicle out yourself! This is one of the most serious mistakes that can be made following an accident involving a house wall. When a car crashes into a building wall, the vehicle’s bodywork often ends up supporting the damaged masonry. If the car is pulled out without due consideration, this can cause parts of the façade or ceilings to collapse suddenly. The vehicle must only be recovered after a structural assessment has been carried out by the fire service or specialist firms.
-
Police report for the preservation of evidence: A police accident report is essential for the subsequent settlement of the claim.
-
Documenting photos and evidence: Take detailed photographs of the vehicle involved in the accident, the damage to the house wall, any cracks in the building and any damaged contents.
In order to document the question of liability and the sequence of events accurately, and to facilitate the settlement of the claim, you should
- Take photographs of the scene of the accident from several angles.
- Approach independent witnesses and make a note of their contact details
- Call the police to have the incident officially recorded
Who pays? The legal and financial arrangements
Once the initial response has been dealt with, the key question regarding the settlement of claims comes to the fore: who will pay for the damage caused by the building accident?
The motorist’s perspective
If the accident was unavoidable for the driver – for example, because they had to swerve to avoid a third party who was turning incorrectly – the claim will be settled by the third-party liability insurance of the person actually responsible for the accident. If the driver caused the accident themselves, the following applies:
- Motor vehicle third-party liability insurance: Under Section 7 of the Motor Vehicles Act (StVG), the vehicle owner is liable for damage caused whilst the motor vehicle is in use. As part of the claims settlement process, the third-party liability insurance covers all justified claims for damage to the property and to third parties’ property.
- Comprehensive motor insurance: It covers damage to your own vehicle caused by the accident (less the contractually agreed excess).
The homeowner’s and tenant’s perspectives
Under Section 249 of the German Civil Code (BGB), the injured party must, as part of the settlement of the claim, be restored to the position they would have been in had the damaging event not occurred. The items of loss eligible for compensation include:
- Facade and masonry restoration: Professional repairs carried out by a building contractor.
- Structural engineer’s and expert’s fees: The costs of commissioning a structural damage report to assess the damage and preserve evidence are included in the recoverable damages.
- Loss of rent & hotel costs: If the building is uninhabitable, the claim settlement covers the costs of alternative accommodation for the residents as well as the landlord’s loss of rental income.
- Commercial depreciation: Where, despite professional refurbishment, the building fabric retains a defect.
- Damaged property: destroyed furniture, electrical appliances or outdoor facilities
Homeowners can also report the incident to their home contents insurer. If necessary, the insurer can advance the costs of emergency repairs and subsequently seek reimbursement from the other party’s motor insurance. A professionally managed claims settlement process ensures that all items of damage are correctly collated from the outset.
Accident victims like you get the best support from fairforce.one.
Have your accident reported now free of charge and without obligation by our regulation specialists.
Heavy machinery: Accidents involving lorries and tractors near buildings
If a lorry crashes into the side of a house or a tractor drives into the side of a house, the kinetic energy of the impact differs drastically from that of a normal car accident.
Special considerations regarding heavy goods vehicle and agricultural accidents:
- Substantial structural damage: Due to the enormous weight of lorries or tractors, it is often not just the façade that is damaged, but the supporting structure is also severely shaken. This frequently results in the fire service or the THW having to put in place shoring measures.
- Liability for vehicle combinations (towing vehicle and trailer): If a lorry with a semi-trailer or a tractor unit with a trailer is involved in a collision with a house wall, both the owner of the towing vehicle and the owner of the trailer may be jointly and severally liable to the injured party. For the property owner, this means that they do not have to apportion the damage themselves for the purposes of settling the claim, but can claim the full amount of the damage.
- Consequential commercial losses: If a tractor or lorry crashes into a commercial property, the settlement of the claim will also cover accident-related business interruptions and loss of earnings.
Special cases: hit-and-run or where the person responsible cannot be identified
If a car crashes into the wall of a house and the driver responsible flees the scene of the accident (Section 142 of the German Criminal Code) or does not have valid insurance cover, there are still ways to obtain financial compensation:
- Hit-and-run / Driver fled the scene: The police will launch an investigation and carry out forensic work. If the perpetrator cannot be traced, and in the event of serious damage, Verkehrsopferhilfe e.V. (the German Motor Insurers’ Guarantee Fund) can act as the point of contact for settling the claim. In addition, in the case of damage to buildings, your own home insurance policy (under the ‘vehicle impact’ cover) often applies.
- Vehicle without insurance cover: In such cases, too, the Road Accident Victims’ Assistance Scheme steps in to protect those affected from financial hardship through no fault of their own.
Quick Check: House wall accidents at a glance
To provide a quick overview, this quick check sets out the procedures and processes involved in claims settlement using the ‘if-then’ principle:
| Accident scenario (If…) | Technical classification | Action required (Then…) |
| Car crashes into the side of a house; driver at the scene | Liability lies with the party responsible’s motor vehicle liability insurance (Section 7 of the Road Traffic Act). | Call the police, take photos, and start the claims process. |
| Vehicle is stuck deep in the masonry | There is an immediate risk of the building collapsing. | Evacuate the house immediately! Do NOT move the vehicle. Call the fire brigade and a structural engineer |
| Driver flees the scene after a collision | Criminal offence (Section 142 of the German Criminal Code), the perpetrator has yet to be identified | Arrange for the police to secure evidence |
| Lorry or tractor crashes into house wall | Joint and several liability of the parties to the contract is possible. | Consult a building surveyor and structural engineer; document any business losses. |
Fact vs. Myth: Dangerous misconceptions about building accidents
To ensure that matters are dealt with in an orderly manner at the scene of an accident, we recommend the following procedure:
| ❌ Myth | ✔ Fact |
| „The car should be pulled away from the wall immediately so that the scene of the accident can be cleared.“ | A dangerous misconception! The crashed vehicle may act as a wedge or support. If it is removed without the approval of structural engineers, there is a risk that parts of the façade could collapse. |
| „Damage to the property must be claimed through the owner’s building insurance.“ | No. First and foremost for the Claims settlement is the motor vehicle liability insurance of the person who caused the accident. The building insurance company serves, at most, as a point of contact for precautionary purposes |
| „A quote from a local tradesperson is always sufficient for settling a claim.“ | In the event of extensive damage to a building, an independent structural damage assessment is essential. A cost estimate does not usually take full account of hidden damage, depreciation or structural assessments. |
| „Tenants have no claim in the event of a collision with the building’s wall.“ | Wrong. Tenants, too, have certain rights under the Claims settlement Entitlement to compensation for damaged household contents or reimbursement of hotel costs if the flat becomes uninhabitable. |
Accident victims in your situation simply get the best support from fairforce.one.
The right steps towards fair claims settlement with fairforce.one
A building-related accident involves a considerable amount of organisational work. With fairforce.one, you can play it safe when settling claims:
- Free initial consultation: You can report the details of the accident to us, with no obligation, using the online form or by calling our freephone helpline on 0800 30 111 60.
- Expert assessment: Our team will assess your situation straight away and discuss the best course of action for settling your claim with you.
- Network & Experts: If required, we can arrange for independent experts to carry out a detailed assessment of all damage to the building.
- End-to-end processing: Specialist partner teams will calculate your claims in full and submit them to the insurer responsible for paying them.
- A clear overview without piles of paper: Through our digital customer information system (KIS), you can keep track of every stage of your claims settlement at any time via your smartphone.
We can’t undo the accident – but we’ll ensure that your claim is settled in a structured, fair and comprehensive manner!
Frequently Asked Questions (FAQ) on the topic of a car crashing into a house wall
Who pays if a car crashes into the wall of my house? (Owner vs. tenant)
The motor vehicle liability insurance of the driver responsible for the accident is liable for damage to the building structure (masonry, structural integrity, windows). It reimburses the owner for the necessary repair and survey costs. If tenants suffer damage to their property (e.g. furniture) as a result of the accident or are forced to move out temporarily, these claims will also be settled through the other party’s liability insurance as part of the claims settlement process.
Who will cover the damage after a car has crashed into my house?
In principle, the at-fault party’s motor vehicle liability insurance will settle the claim. As accurately assessing all building damage, loss of value and business interruption costs is a complex process, it is advisable to seek professional support with the claims settlement from experts such as fairforce.one. We coordinate the independent damage assessment and take the pressure off you throughout the entire claims process.
Is it necessary to consult a structural engineer following an incident involving a house wall?
As soon as cracks appear in the masonry, windows become warped or load-bearing structural elements are affected, a structural engineering report is absolutely essential. The costs incurred for this report are included in the recoverable damages during the claims settlement process.
Does it make a difference to the settlement of a claim if the driver has had a medical incident?
No, strict liability under Section 7 of the Road Traffic Act (StVG) applies regardless of whether the driver caused the accident through a driving error or a sudden health problem. The other party’s liability insurer remains the relevant point of contact for settling the claim.